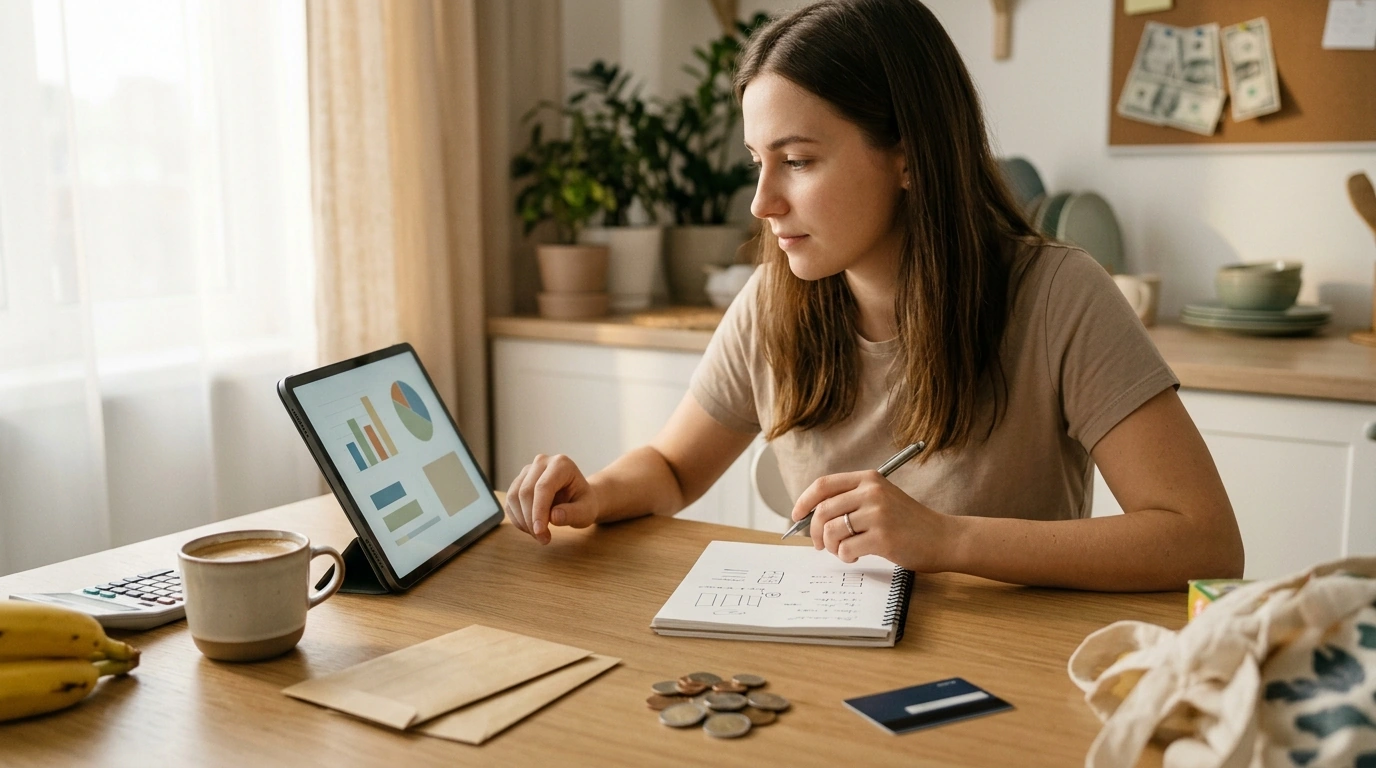
A workable budget doesn’t require complicated math or cutting every small pleasure from your life. It starts with knowing what comes in, deciding what matters most, and giving your money a plan before it gets spent.
Start with your take-home income for a typical month. List essential costs such as housing, utilities, groceries, transportation, insurance, and minimum debt payments. Then add flexible spending, savings, and occasional bills that may not arrive every month. If your income changes, build your plan around a conservative estimate and adjust when you know more.
Compare your planned expenses with your income. If the total is too high, look first for costs you can reduce or pause, rather than assuming you can save an unrealistic amount. A digital budget can make these categories easier to organize and update. Visit our budgeting guide for another way to plan and save more.
Review recent transactions and look for spending that doesn’t match your priorities. You might switch to a lower-cost plan, prepare more meals at home, compare recurring subscriptions, or set a weekly limit for nonessentials. Pick one or two changes at a time so your budget stays realistic and easier to follow.
Make saving a planned expense instead of waiting to see what remains. Choose an amount that fits your current budget—even a small, consistent contribution helps you build the habit. If possible, move it to savings soon after payday.
Choose a method you’ll actually use: a notebook, spreadsheet, or digital planner. Record purchases as they happen, or set a brief weekly check-in to compare spending with your category limits. When a category runs low, decide whether to slow down, move money from a lower-priority category, or revise the plan. Tracking is a tool for making decisions, not a reason to feel guilty.
Plan for irregular expenses such as annual fees, school costs, car maintenance, or gifts by setting aside a little each month. Keep a modest amount for enjoyment, too, so your plan doesn’t feel like an all-or-nothing challenge. If you share expenses with someone, agree on priorities and spending limits together.
Review your budget monthly and after major changes in income or expenses. Our team recommends treating it as a flexible plan: keep what works, adjust what doesn’t, and celebrate steady progress rather than expecting perfection.
Cover urgent essentials first, then review your categories for money you can temporarily redirect. If needed, adjust your savings contribution or spending plan for the month and make a plan to rebuild your cushion afterward.


Leave a comment